 Murmur
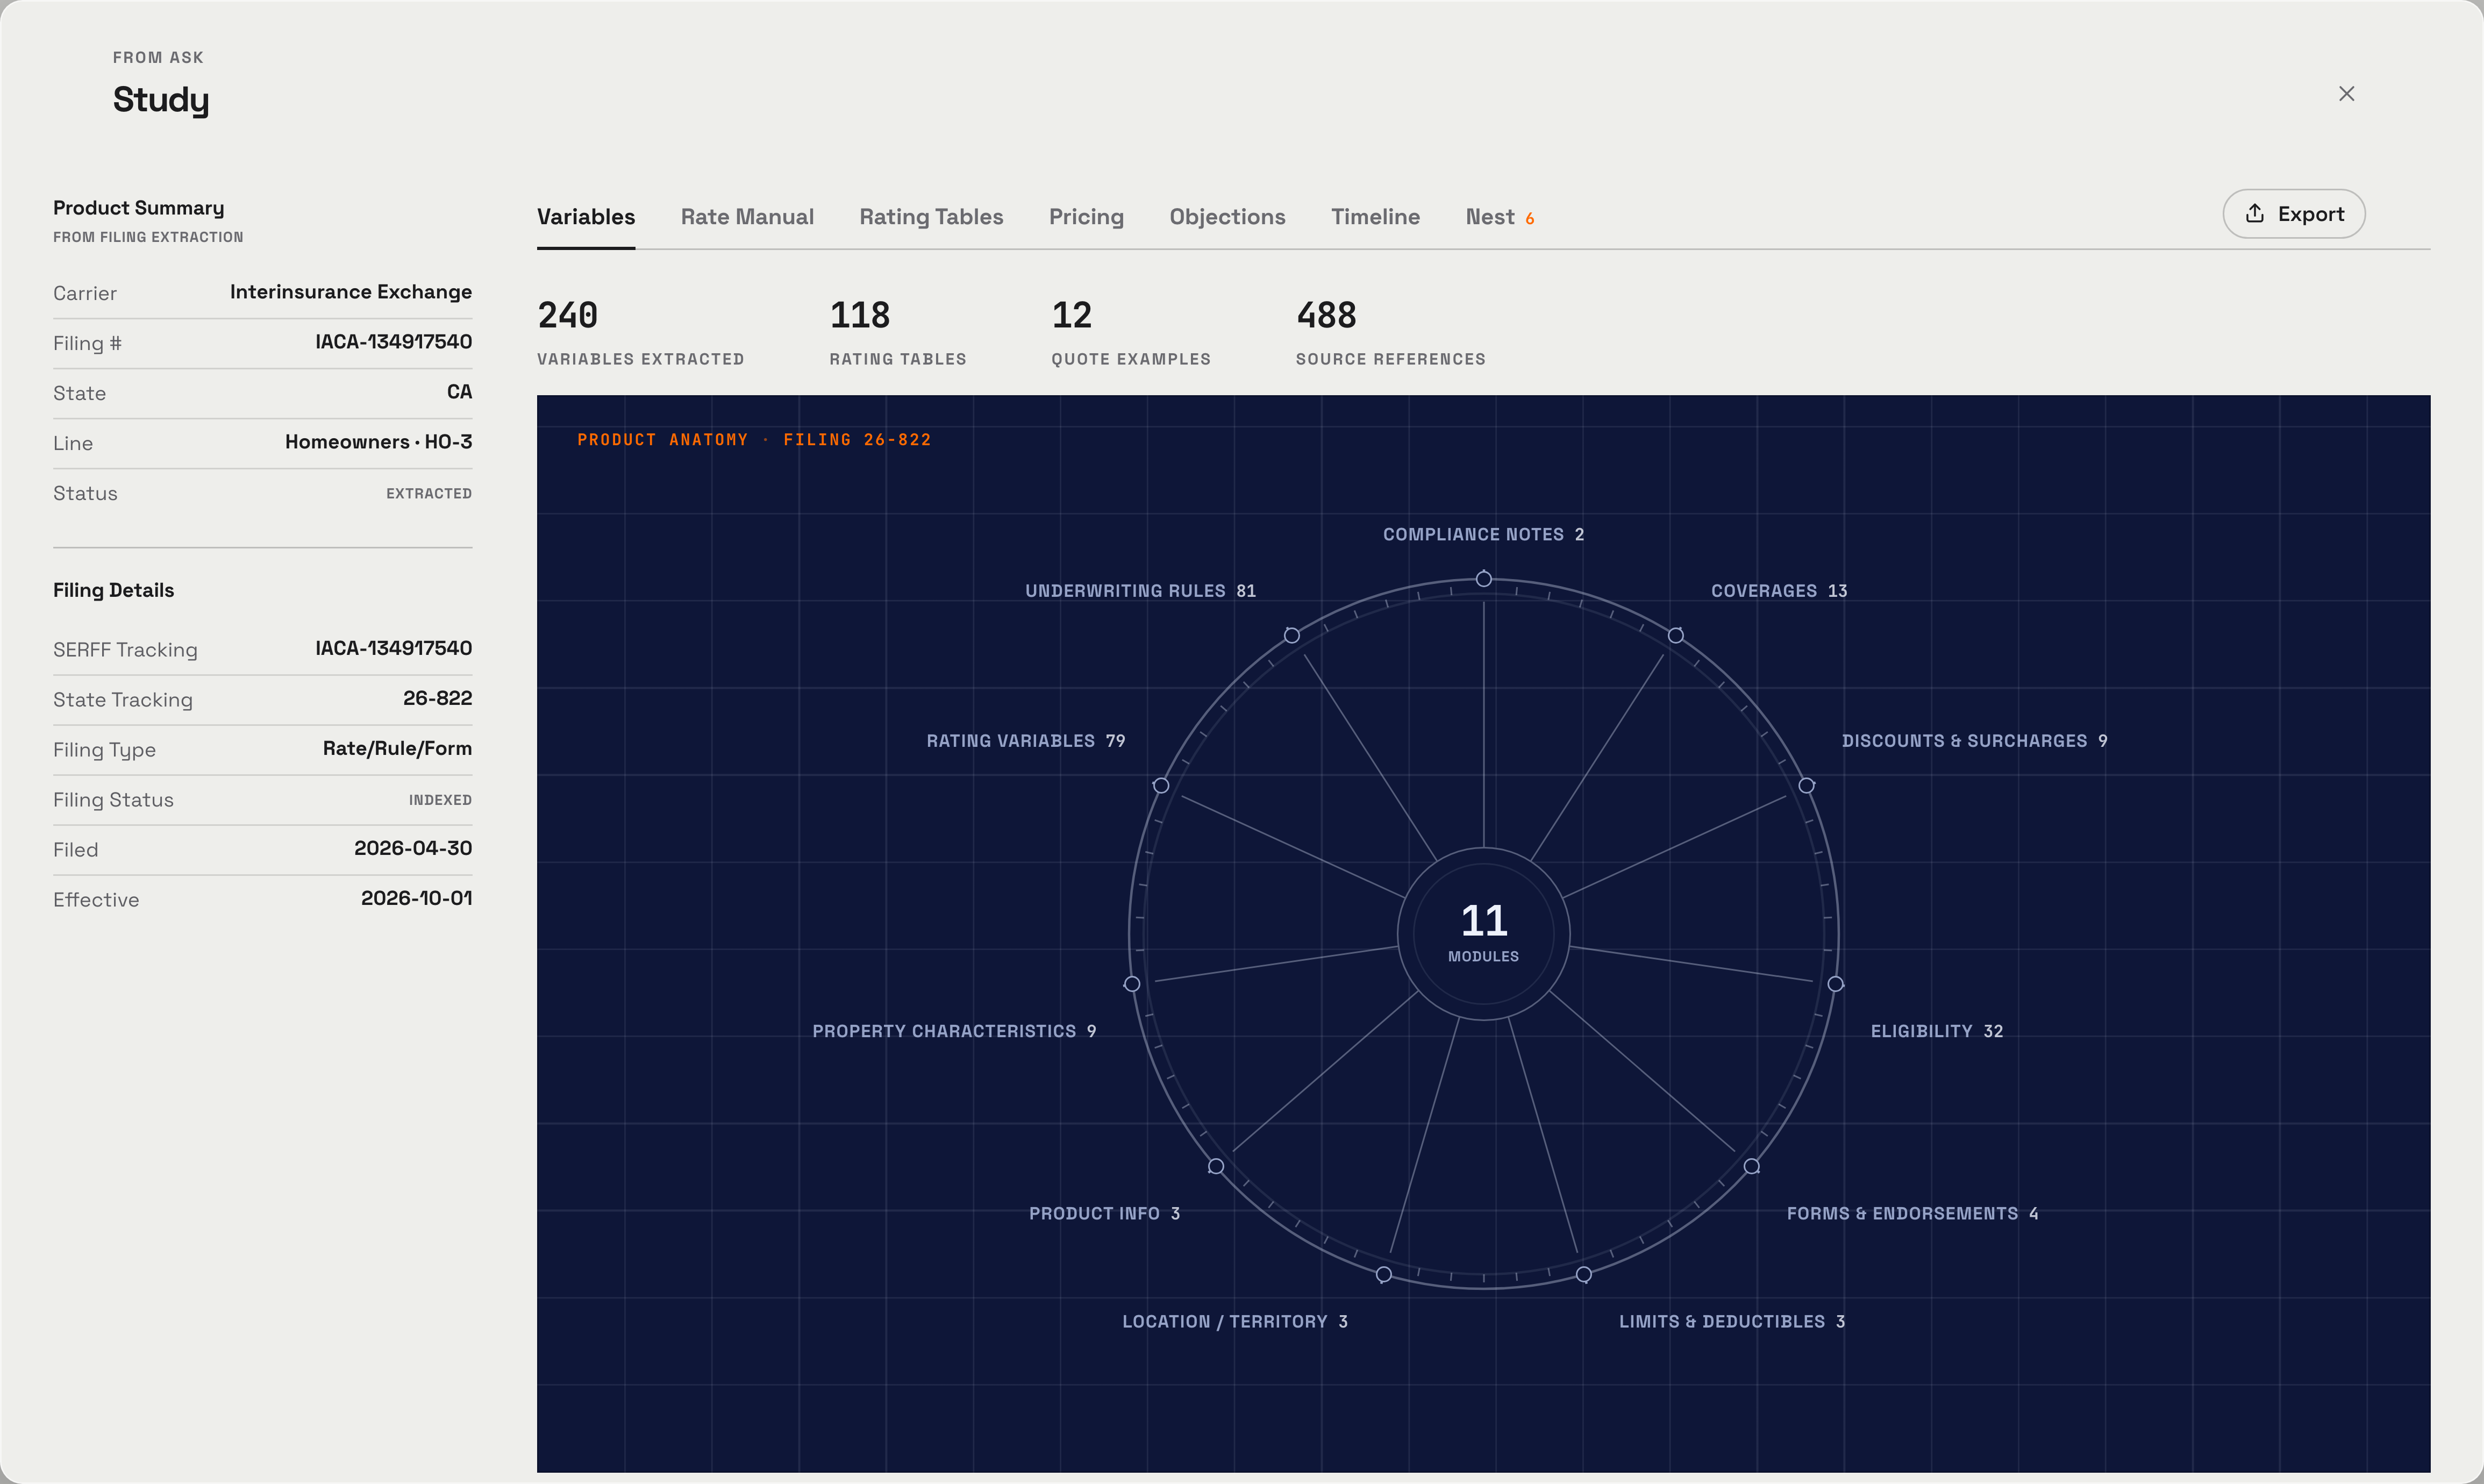
Study the filing
Understand its structure.

Insurance runs on
this information.
One connected insurance intelligence foundation.
What’s worth a closer look?
Which California homeowners filings changed their credits or discounts this year?
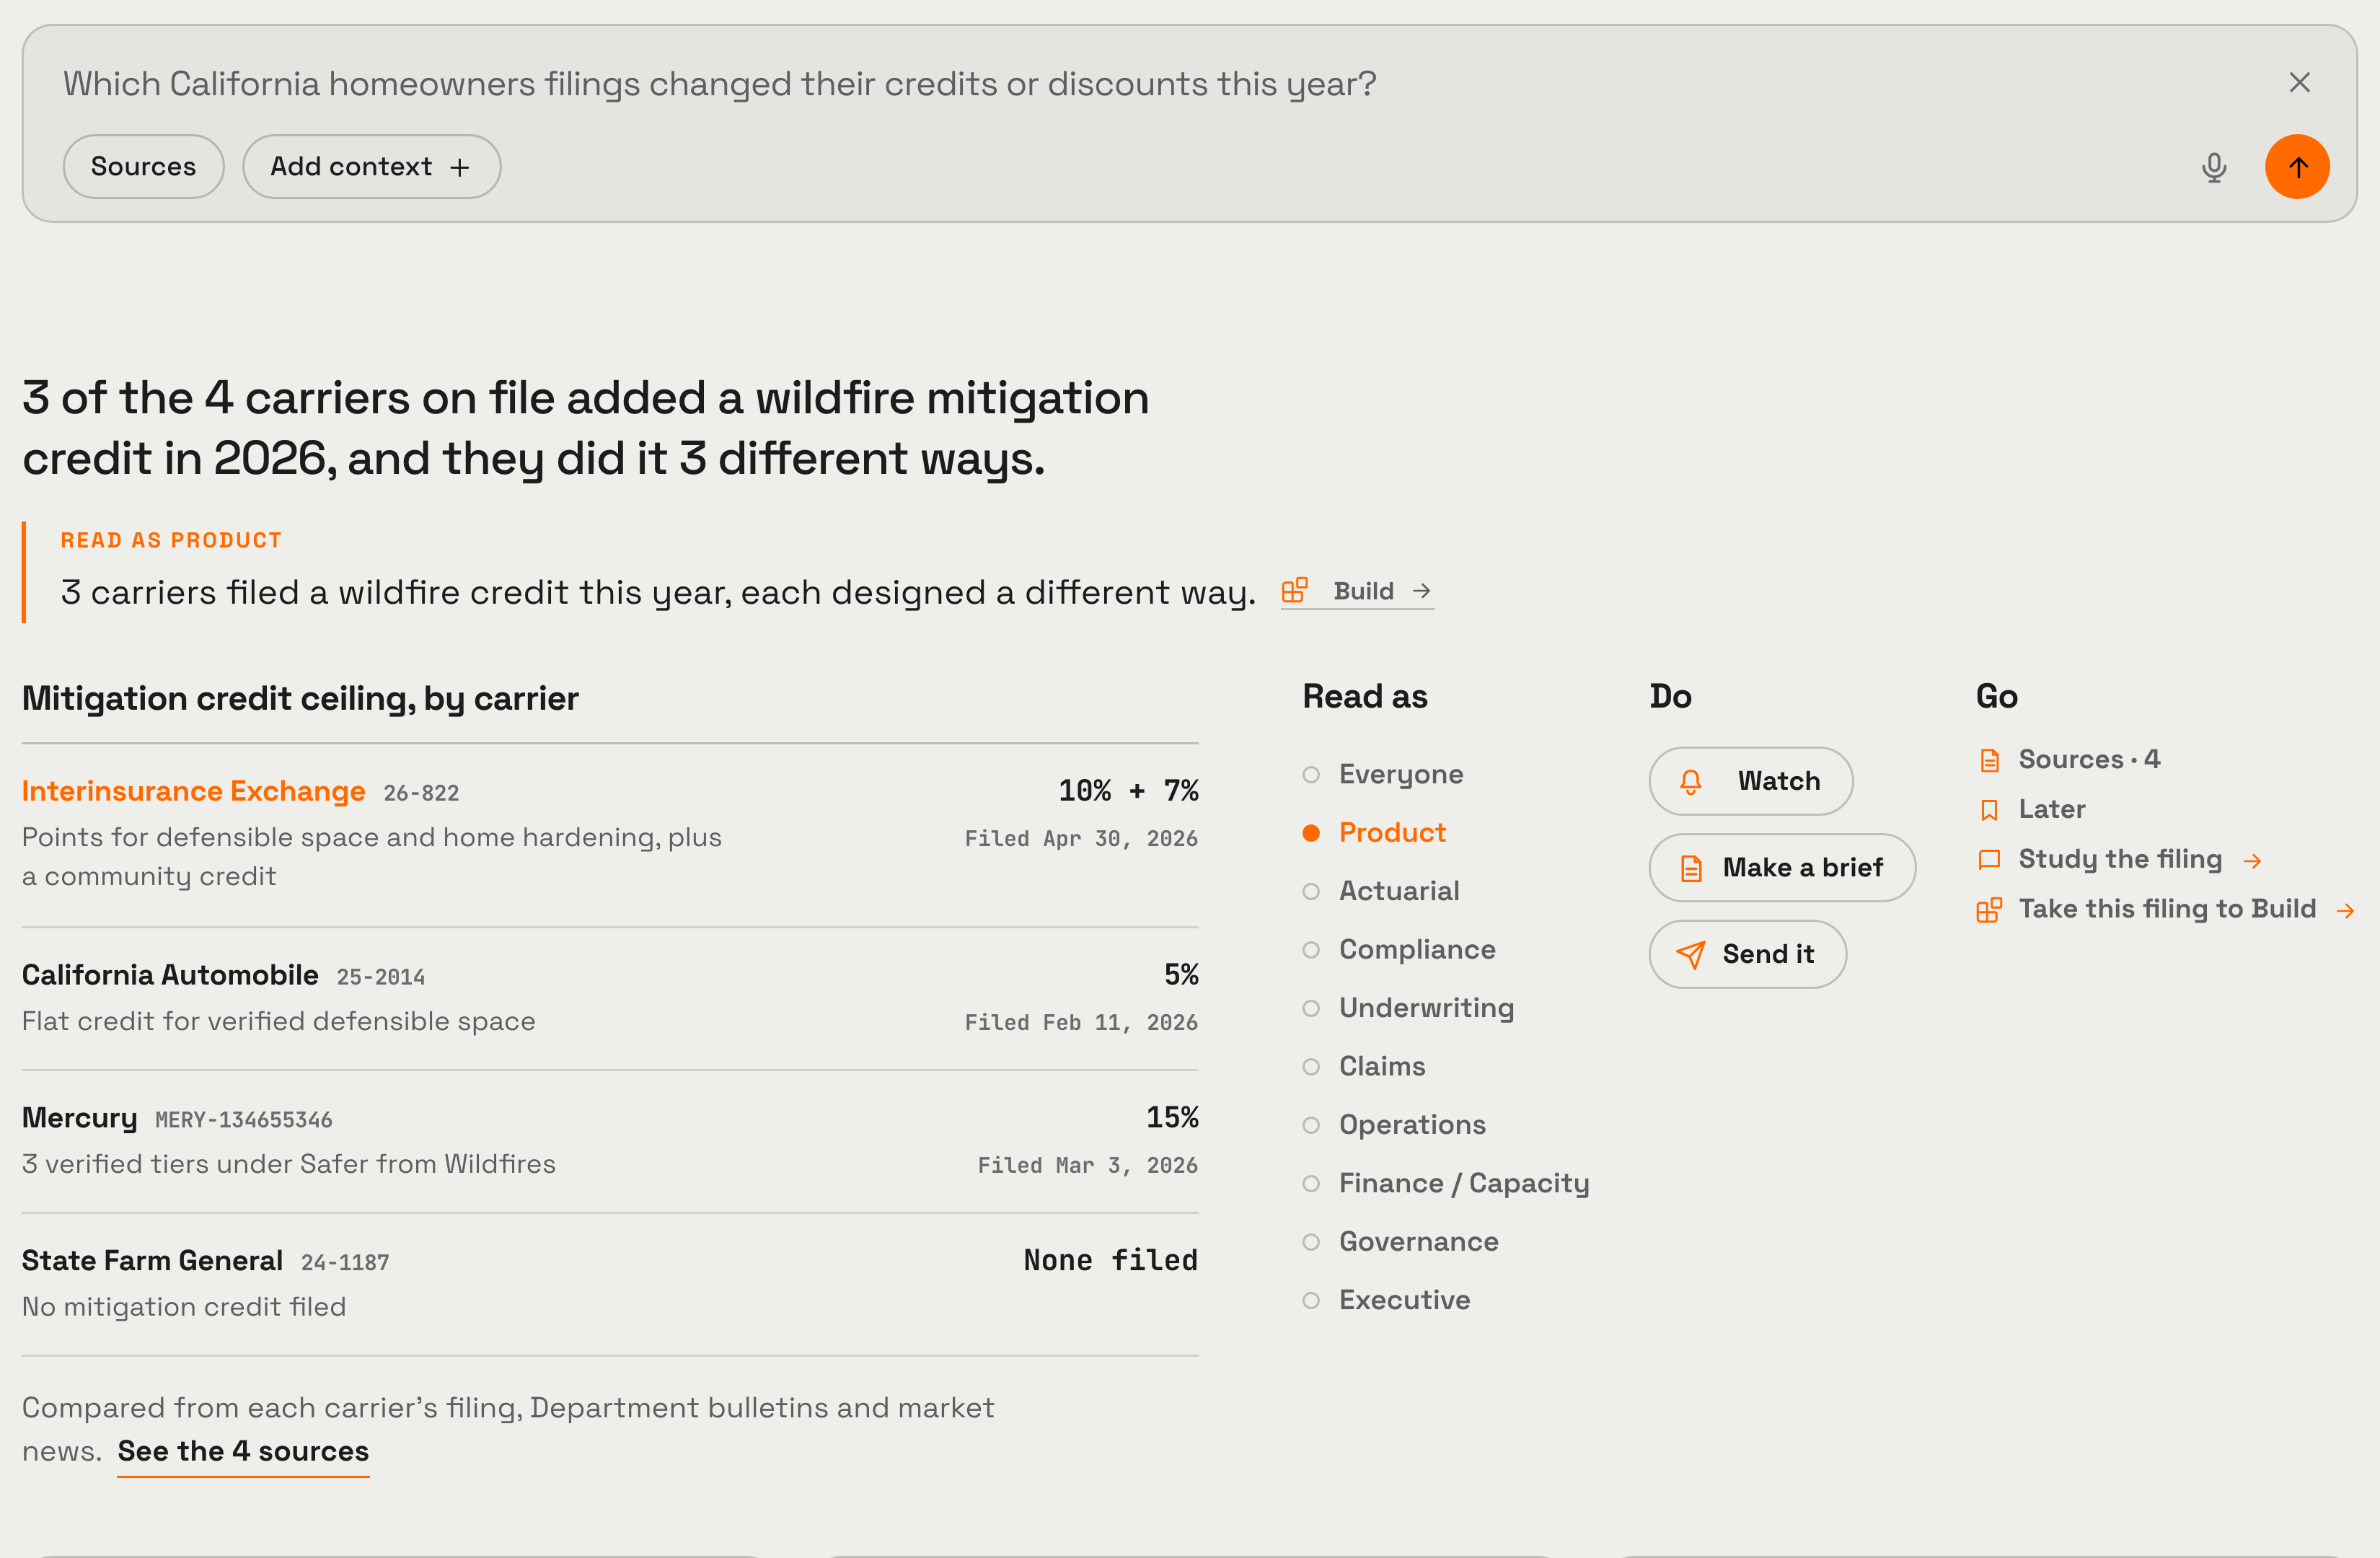
THE EXPERIENCE WE ARE BUILDING
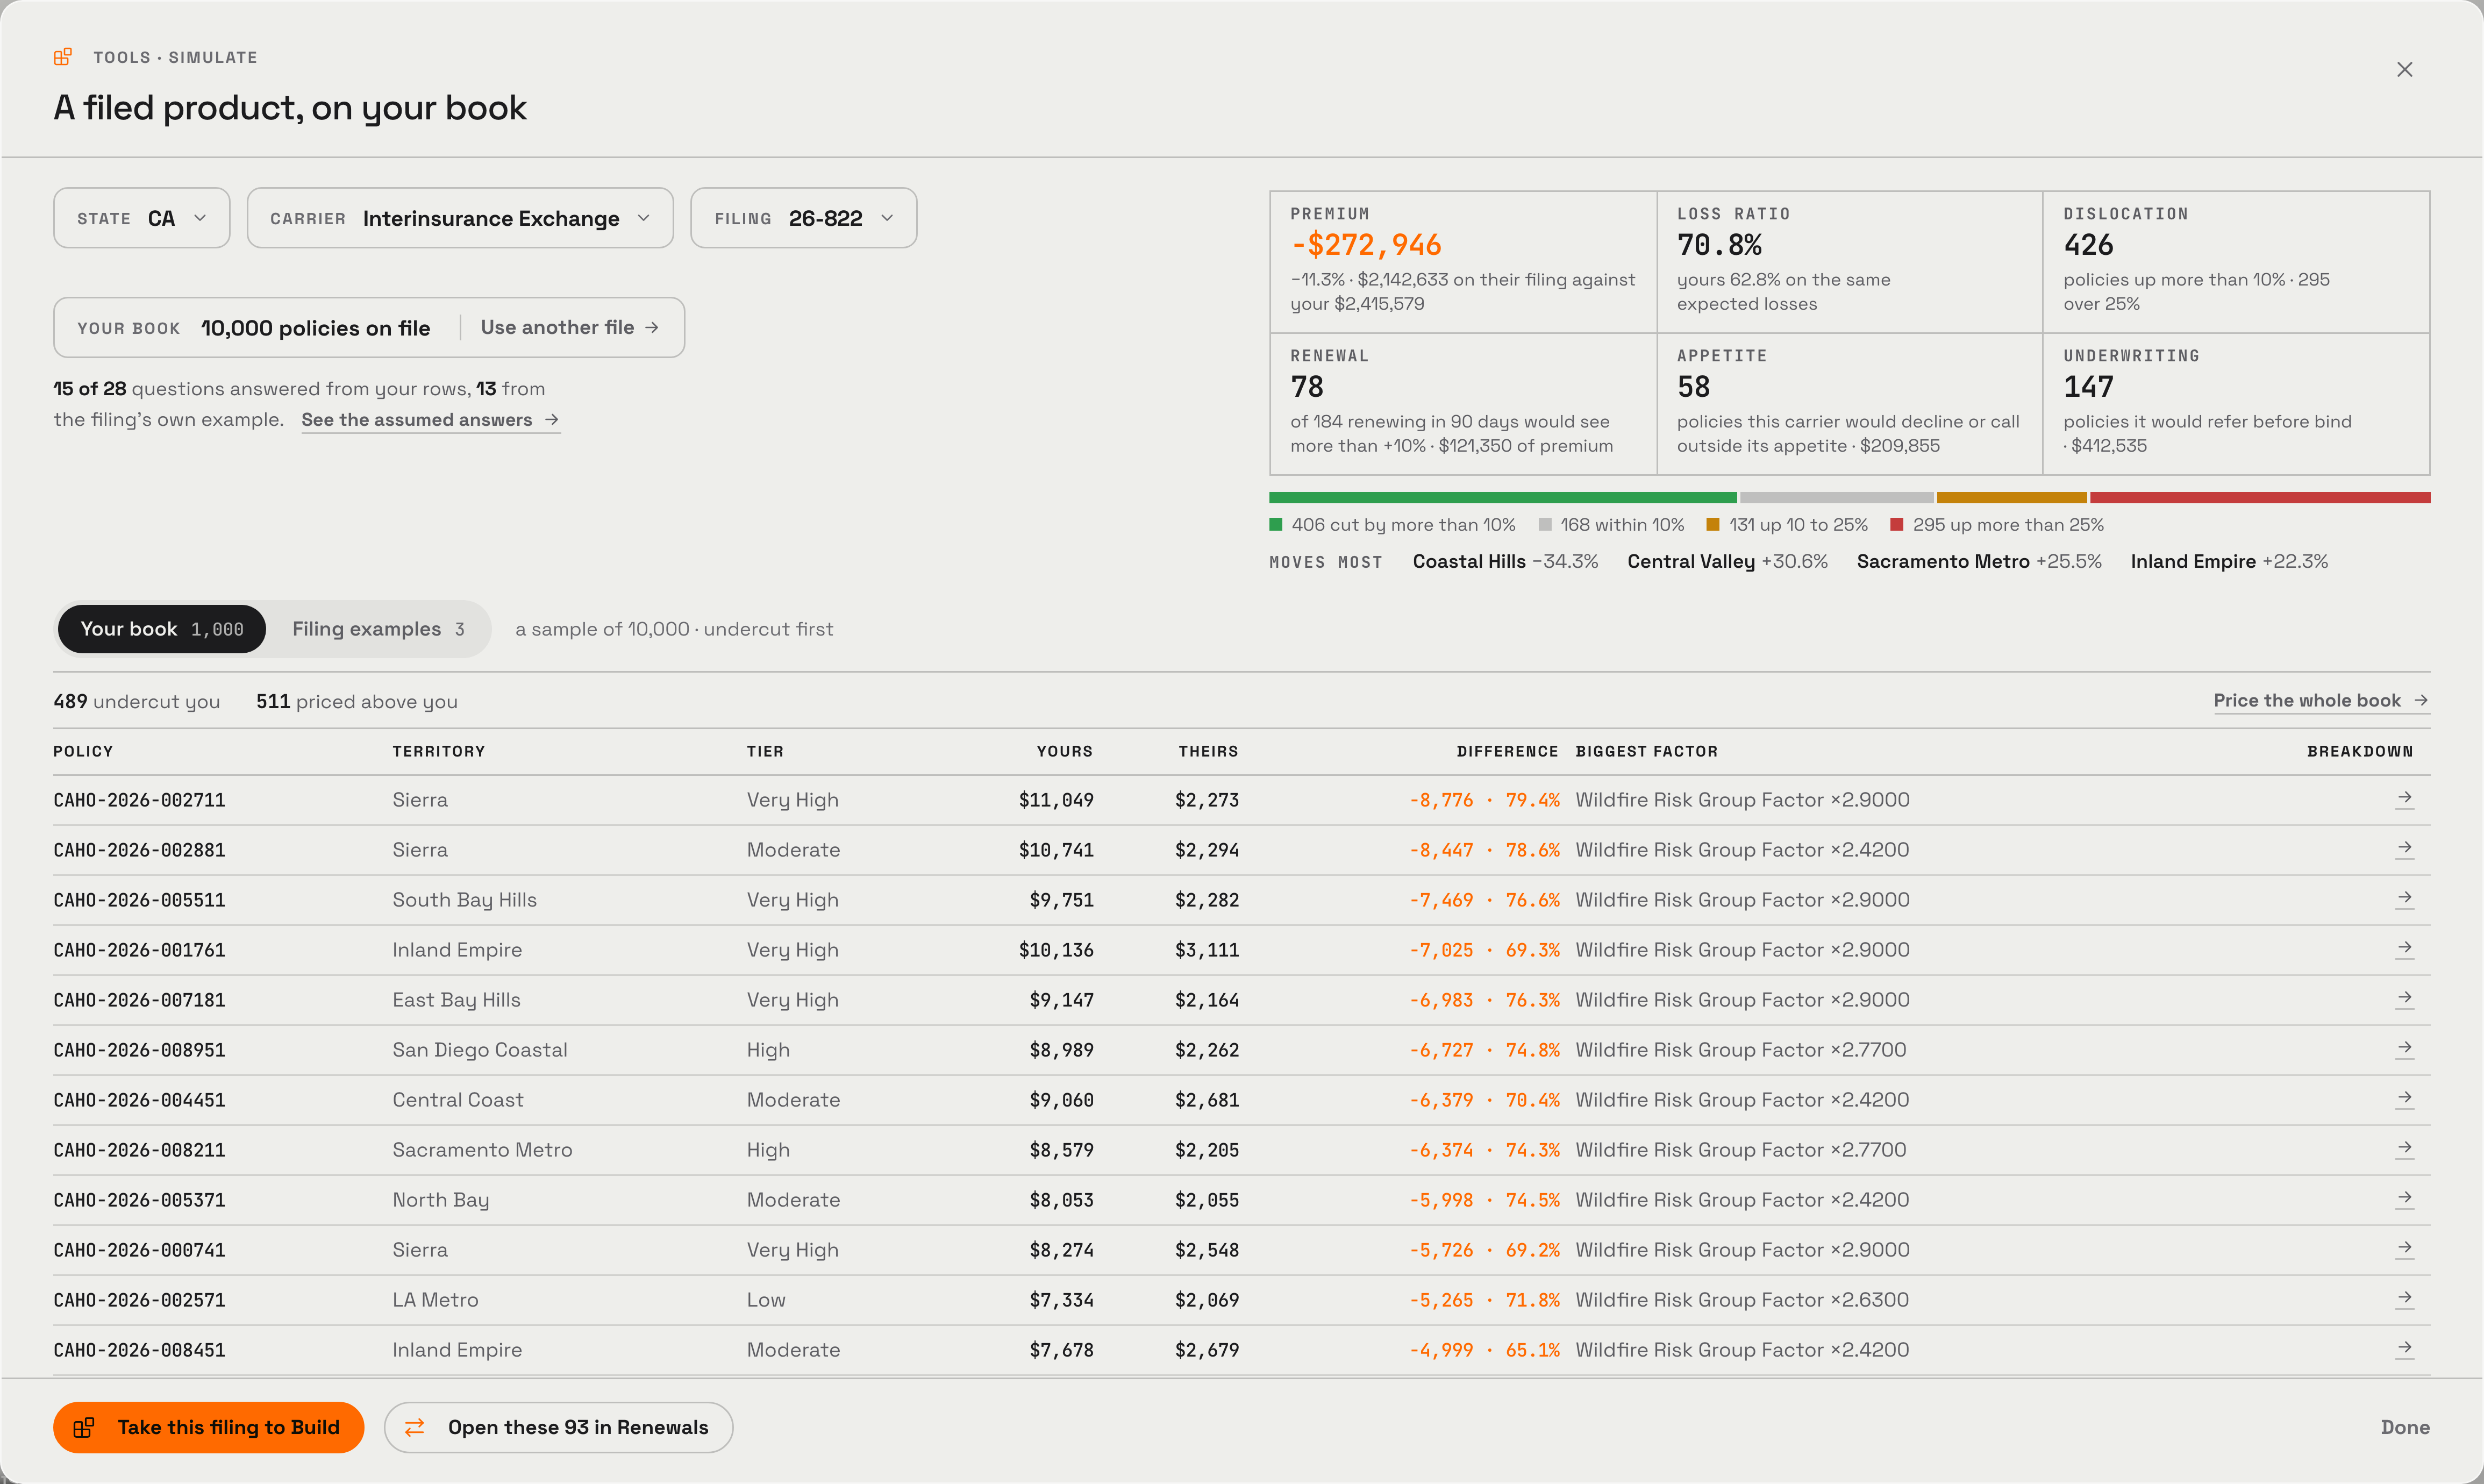
See how a competitor would price the same policies in your book.
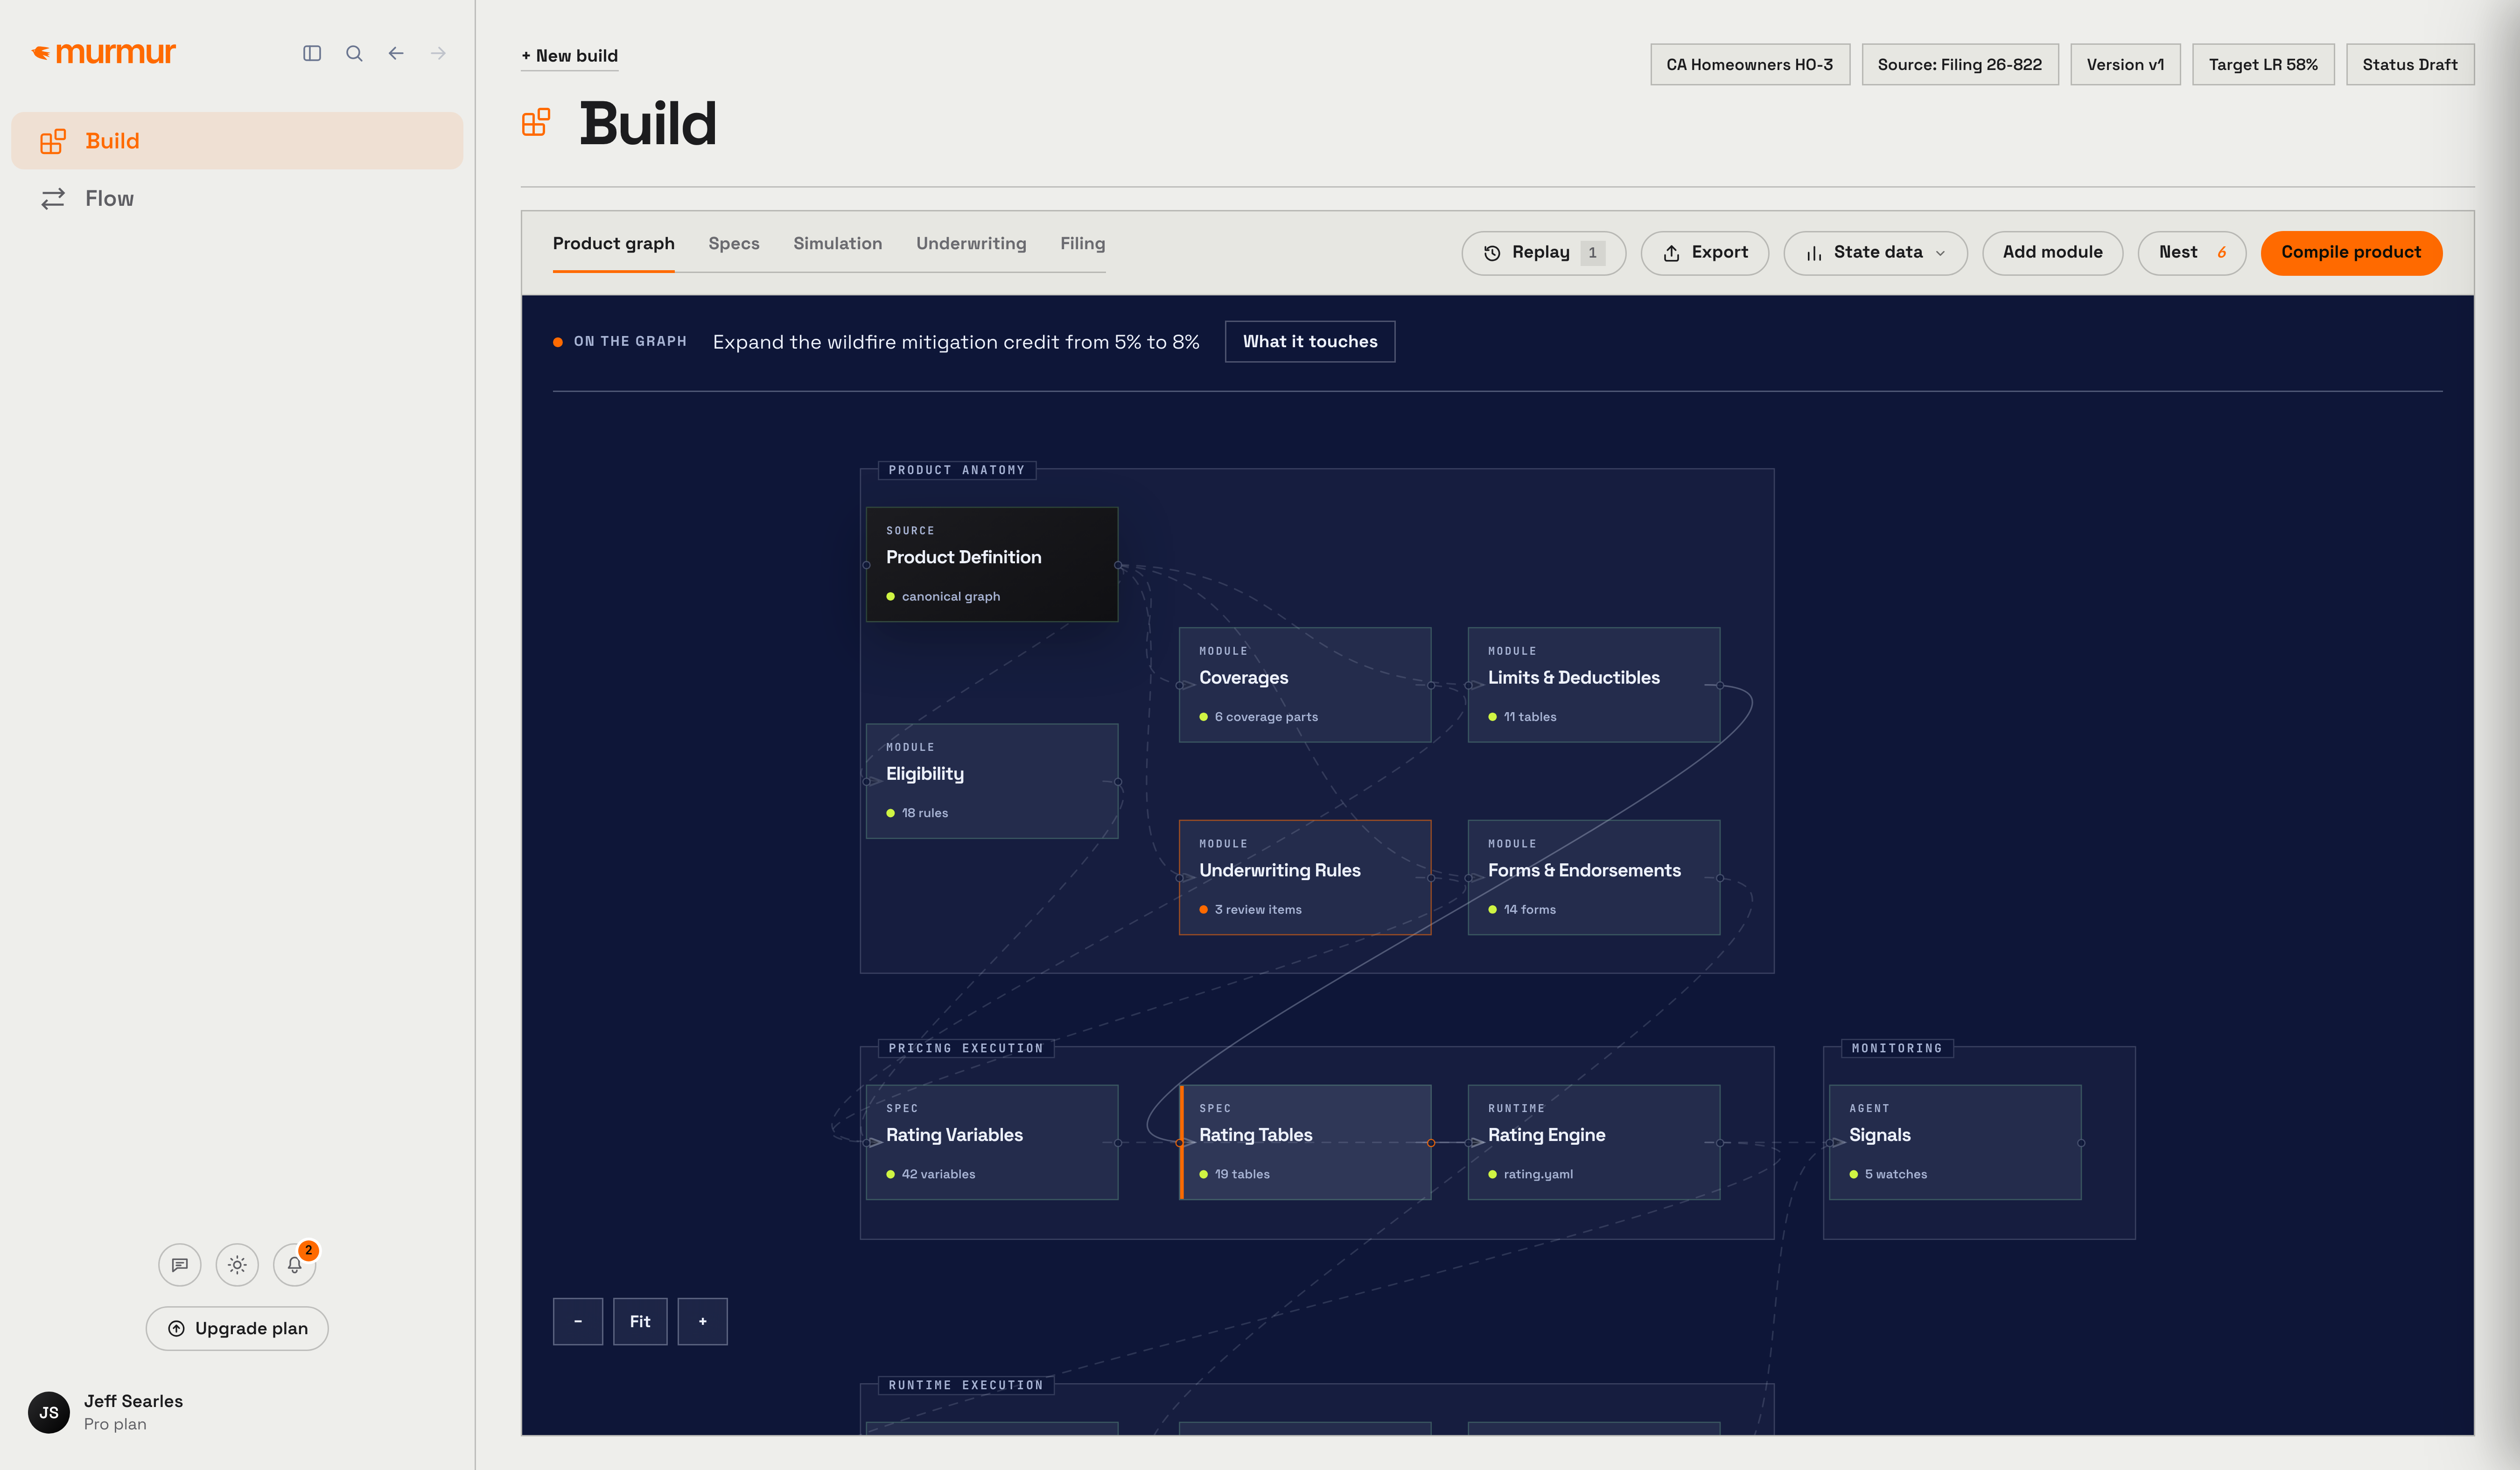
Understand its structure.
Develop your insurance product.
WHY MURMUR
Filings. Bulletins. Market signals.
Traceable to the source.
Coverages. Rules. Rates.
Connected in a product model.
Your product. Your decisions.
Your book of business.
BUYER SIGNALS
EARLY BUYER DISCUSSIONS
Competitive intelligence.
Product development and scenarios.
WHAT WE NEED TO DELIVER
GO TO MARKET
Competitive product research.
An annual agreement with a paid pilot.
More states. More products. More connected workflows.
Carriers & MGAs
Managing general agents (MGAs)
underwrite insurance on a carrier’s behalf.
| State 1 | State 2 | State 3 | State 4 | |
|---|---|---|---|---|
| Product 1 | Start here | Potential expansion | Potential expansion | |
| Product 2 | Potential expansion | Potential expansion | ||
| Product 3 |
BUSINESS MODEL
Planning assumptions: 15 customers at $250K ACV. Expansion revenue is excluded.
THE OPPORTUNITY
Working organization universe
Size-based pricing: $100K–1M
Modeled pool after overlap allowance
Assumed contracts: $75K–150K
Research, pricing and product advice
Firm count and pricing under review
Agency pool: Big I 2024 study; ~9,200 above $1.25M revenue, less 1,100 assumed overlap. All pricing is unvalidated. View assumptions online ↗
THE RAISE
Put Murmur into production.
Turn buyer interest into customers.
Reliable infrastructure.
Security and buyer requirements.
Customer onboarding.
Agreed product scope and value.
Annual relationships.
A path to broader account use.
Two-year plan funded by the raise and modeled customer collections.
THE TEAM
Led Go as an MGA and served on its carrier executive team. CEO and co-founder of Varda, acquired by Trōv.
Co-Founder and CTO of Go Insurance. Built its rating, underwriting and policy infrastructure.
Product leadership at Esurance, Go and Acrisure. Experience across insurance product development and underwriting.
EVP, Gallagher Re Program Solutions. Previously led Digital Partners in North America.
Techstars and Alchemist advisor experience. Enterprise SaaS and cloud leadership.
InCountry co-founder. Former MileIQ adviser.
Livefyre VP, Business & Corporate Development.
APPENDIX · PROPOSED OPERATING PLAN
Revenue included · 15 annual customers at $250K ACV by month 24
| Planning measure | Year 1 Months 1–12 | Year 2 Months 13–24 |
|---|---|---|
| Annual customers at year-end | 1 | 15 |
| Team at year-end | 5 employees + 1 contractor | 8 employees + 1 contractor |
| People costs | $891K | $1.669M |
| Corpus AI processing + contingency | $468K | $113K |
| Customer AI inference | $3K | $226K |
| Data access, infrastructure + other operations | $408K | $588K |
| Implementation + customer support | $42K | $431K |
| Setup, security, recruiting + equipment | $162K | $85K |
| Total spending | $1.973M | $3.112M |
| Revenue earned during the year | $29K | $1.954M |
| Year-end ARR | $250K | $3.75M |
| Cash collected | $0 | $3.400M |
| Cash remaining at year-end | +$1.027M | +$1.315M |
$3M raise + projected customer collections fund the plan, with $1.315M cash remaining.